

Top Fintech Companies in Los Angeles, CA (342)

By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
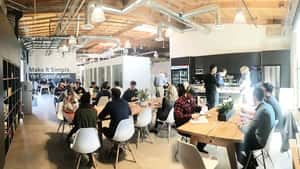
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR reportedly rose from $100M in early 2024 to $200M by January 2026, indicating rapid top-line momentum driven by upmarket wins and adoption of AI agents. This step-up is reinforced by multi-year growth recognition such as Deloitte’s Technology Fast 500 placements.
Investor Backing & Capital Strength: A $100M Series E at a $1.6B post-money valuation in April 2024 provides substantial resources for continued product investment and international expansion. This late-stage funding signals confidence in the company’s scaling prospects.
Market Expansion: New offices in London and Sydney, stronger growth in EMEA, and the largest customer to date in Germany point to widening international reach. Alliances with firms such as EY further extend access to large finance transformation programs.
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with Jack Henry for Visa Direct enablement and integrations like LoanPro’s native Moov processor (June 2026) point to expanding distribution and credibility with financial institutions and lenders. Additional ecosystem ties (e.g., Plaid, Currencycloud, Google Cloud Marketplace) reinforce growing channel reach and capability breadth.
Innovation-Driven Growth: Ongoing 2026 documentation and dashboard updates—covering instant-rail support (RTP/FedNow), new partner billing features, surcharging, and versioned API releases—indicate sustained product velocity. Becoming a licensed card/acquiring processor and highlighting a Visa processing relationship in 2024 suggest broadening use cases over subsequent years.
Market Expansion: Operating fintechdevcon (listed as organizer in 2025–2027) expands developer and partner pipelines that often precede commercial wins. New integrations and ecosystem activity through 2025–2026 signal growing platform adoption beyond initial beachheads.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Record adjusted operating income and margin accompanied the growth, with management lifting 2026 adjusted operating income guidance to a higher margin level. Operating leverage was emphasized alongside strong second‑quarter results.
Resilient & Sustainable Growth: Gross profit accelerated year over year into Q2 2026 (after an even stronger Q1), and full‑year 2026 gross profit guidance was raised meaningfully. Leadership framed gross profit as the clearer indicator of underlying momentum given revenue mix effects.
Cost & Operational Efficiency: Efficiency measures, including running a leaner organization, boosted margins and contributed to record profitability. Leaders also pointed to continued strength into the second half with healthy monetization and risk metrics, indicating efficient scaling.
We’re a Detroit-based company obsessed with helping our clients achieve the dream of homeownership and financial freedom. Our flagship business, now known as Rocket Mortgage, was founded by Dan Gilbert in 1985. Since then, we’ve revolutionized the mortgage industry – twice – and taken our place as the industry leader. Today, the Rocket brand is synonymous with providing simple, fast...

Rocket's Top Stability & Growth Strengths
Profitability: GAAP net income rose to $229M in Q2 2026 from $34M a year earlier, with adjusted net income at $441M, and management described it as the most profitable quarter in four years. Adjusted EBITDA reached $766M, underscoring improved operating leverage.
Strong Revenue Growth: Total revenue, net, was $2.78B in Q2 2026 versus $1.45B in Q2 2025, and adjusted revenue was $2.76B versus $1.43B. Trailing twelve‑month revenue reached $10.02B, reflecting a substantial year‑over‑year increase.
Strong Market Position & Advantage: Record market shares were achieved in Q2 2026—purchase at 6.2% and refinance at 14.3%—with total closed loan volume of $49.1B. A roughly $2.0T servicing portfolio across 9.1M loans provides recurring fee income and a large recapture funnel.
Scratch is a dynamic and innovative fintech company at the forefront of patient lending and payment processing, serving a network of over 17,000 veterinary practices across the United States and Canada. Our mission is to revolutionize the veterinary financial experience, ensuring pet parents have seamless access to the treatments they need without the burden of financial stress.

Scratch Financial's Top Stability & Growth Strengths
Market Expansion: Provider counts progressed from more than 10,000 practices in 2022 to “over 17k” by September 2025 and “+18k” cited in 2026, indicating broader clinic adoption across the U.S. and Canada. Partnerships with multi‑location groups like CareVet and channels like Blue Rabbit further extend distribution.
Investor Backing & Capital Strength: A $35M Series C in 2022, ongoing issuance via WebBank, and a May 2026 purchase facility with Victory Park Capital signal strong funding access to scale originations. These moves point to expanded receivables capacity to meet rising demand on the platform.
Strong Revenue Growth: Inc. 5000 placements across 2024–2026 (e.g., No. 430 in 2025 and continued inclusion in 2026) reflect sustained multi‑year expansion. The repeated recognition indicates momentum rather than a one‑off spike.

At Revel, we are revolutionizing the way the world’s most critical hardware is controlled—across aerospace, automotive, energy, and manufacturing sectors. Our next-generation software stack combines an intuitive command/control interface, a specialized programming language tailored for hardware control, and a high-performance runtime environment. We empower engineers to build, test, and deploy critical systems rapidly, reliably, and safely.

Revel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Significant capital inflows are evident with a $150M Series B led by Index Ventures and corroborated by multiple third parties, implying a valuation just over $1B. This provides substantial resources and runway to scale product and go-to-market.
Market Expansion: A clear move beyond rocket test stands into industrial control across nuclear, oil and gas, water treatment, power, defense, data centers, and biomanufacturing is described. This broadening suggests a larger addressable market and multi-sector growth potential.
Customer Loyalty & Retention: Conversion from pilots to paying customers is described as universal, and a flagship account reports standardizing the platform across hundreds of assets with over 80 instances. These observations indicate deepening usage and stickiness within early accounts.
Octus, was founded in 2013 with a simple conviction: credit decisions deserve clarity, not chaos. Markets were fragmented. Intelligence was gated. Data lived in silos. Professionals were forced to stitch together incomplete pictures while the clock kept running. We built Octus to change that. Octus is the essential credit platform that tracks the entire credit lifecycle. From origination and underwriting to...
Octus's Top Stability & Growth Strengths
Product Line Growth: Launches of CreditAI (March 10, 2026) and the MCP connector (July 14, 2026) show active expansion of AI-enabled features and distribution into third-party LLMs. Additional rollouts like CreditAI Vault and covenant/term analytics in 2025 reinforce ongoing product investment.
Market Expansion: Acquisitions of Sky Road (2025) and LevPro (2026) extend Octus from intelligence and data into portfolio management and trading workflows for CLO and private-credit managers. A 43,000‑square‑foot New York office lease and reported growth in global users suggest a broader footprint and installed base.
Strong Hiring & Retention: Built In lists roughly 808 employees, seven offices, and active hiring across functions, and other sources describe substantial onboarding in 2025. These indicators point to headcount expansion supporting scale.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising rapidly, with Cash App up 31% year over year in Q2 2026 and companywide gross profit also expanding. Guidance was raised on the strength of Cash App and Square, underscoring ongoing profit momentum.
Cost & Operational Efficiency: Management is prioritizing gross profit per employee and operating margins, aiming to run a smaller company while continuing product and user growth. The February 2026 restructuring was framed around “disciplined growth” and AI‑driven efficiency.
Resilient & Sustainable Growth: Users and engagement are trending up, with about 59 million monthly actives at end‑2025 and accelerating inflows per active alongside rising “primary banking” usage. Momentum carried into 2026, with strong early‑year gross profit growth supporting raised full‑year outlook.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue has increased over consecutive fiscal years to $638.4 million in FY26, building on gains reported in FY24 and FY25. This points to continued top-line expansion.
Investor Backing & Capital Strength: A significant minority investment from New Mountain Capital was announced on August 1, 2025 to accelerate growth, technology and acquisitions under an alternative practice structure. This provides funding capacity to scale and pursue M&A.
Innovation-Driven Growth: The mix is shifting toward advisory and technology services (nearly half of revenue per the firm), with capability additions reinforcing this pivot. The CompliancePoint transaction further broadens cybersecurity, privacy and compliance offerings.


Traditional firms rely on interviews, retroactive documentation, and billable hours. Onshore applies AI at the point of substantiation, providing documentation tied directly to source data and pairing it with expert review. The result is defensible, audit-ready work delivered in weeks, not quarters. We help companies claim R&D Tax Credits, 179D Deductions, and Cost Segregation with proof, not process. 500+ companies have trusted Onshore...
Onshore's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $31 million Series B led by FPV Ventures with participation from Vertex Ventures, Y Combinator, Restive/PruVen and ADP Ventures provides fuel to scale product and go‑to‑market. Independent listings and investor notes corroborate the round and funding trajectory.
Product Line Growth: The company reports expanding from R&D credits into 179D energy‑efficient building deductions, cost segregation, and plans to extend automation into broader tax workflows. This broadened mandate positions it to move beyond credits and incentives.
Strong Hiring & Retention: Public materials list multiple open roles across Finance, Sales, Operations, and Client Success in several U.S. locations. These postings indicate active team expansion aligned with a scale‑up phase.
Named one of the top 10 Credit Union in California by Forbes, First Entertainment Credit Union has been the financial ally since 1967 for the creators of entertainment and those who support them. With more than 2.1 billion in assets and over 90,000 members, we are constantly looking for talents to help us build a high trust, high performance and...

First Entertainment Credit Union's Top Stability & Growth Strengths
Profitability: Net income was $6.4 million in 2024, indicating the institution remained solidly profitable. These earnings are described as positioning the credit union for future growth.
Investor Backing & Capital Strength: The net‑worth ratio rose from 8.94% at year‑end 2023 to 9.69% at year‑end 2024, reflecting stronger capitalization. Early 2026 figures around 10.08% sustain this improvement.
Market Expansion: The CineFi digital brand launched in January 2026 to reach entertainment professionals in the Atlanta metro area, extending reach beyond Southern California. New employer partnerships in 2024 (e.g., Lionsgate and MBS Group) further broadened access within its niche.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Square gross profit and payment volumes are rising with signs of acceleration in 2026; Q2 2026 gross profit reached about $1.16B and GPV increased at a low‑teens rate year over year. Management also raised the full‑year outlook at the Block level, indicating momentum in which Square is contributing.
Market Expansion: Traction with larger, multi‑location sellers and strong international GPV growth indicate expansion beyond very small businesses. U.S. GPV also accelerated to its strongest pace since Q2 2023, complementing faster non‑U.S. growth.
Innovation-Driven Growth: Hardware and AI are highlighted as fast‑compounding capabilities, and Square Financial Services has begun processing acquiring volume. An expanded ISO and partner ecosystem is bringing in more new sellers and deepening product adoption.
SentiLink is the leading fraud intelligence company, providing financial institutions and fintechs with purpose-built solutions for identity verification and fraud prevention. Our products detect synthetic fraud, identity theft, and hard-to-detect first-party fraud in real time — helping partners stop losses before they happen while approving more legitimate customers. Founded in 2017 by Naftali Harris and Max Blumenfeld, creators of the risk...

SentiLink's Top Stability & Growth Strengths
Strategic Partnerships: Availability of SentiLink’s Identity Theft Score on the FICO Marketplace broadens distribution to FICO Platform customers, and a 2026 FICO Industry Vanguard Decision Award signals traction within bank decisioning ecosystems. Being listed on FICO Marketplace also lowers integration friction for institutions already on FICO.
Market Expansion: Selection by Florida’s Agency for Health Care Administration to support the state’s 2026 Medicaid Integrity Initiative marks expansion into public‑sector healthcare use cases. Coupled with wider distribution via FICO, this points to simultaneous vertical (government/healthcare) and horizontal (channel) expansion.
Strong Hiring & Retention: Active postings across engineering, data, and leadership roles—and third‑party trackers showing “actively hiring” status—indicate headcount growth in mid‑2026. The February 2026 appointment of a Chief Revenue Officer underscores an explicit push to scale sales and partnerships.
MarketAxess is on a journey to digitally transform one of the world's largest financial markets, enabling the shift from analog, phone-based trading to a fully electronic marketplace. Why does this matter? Because our platform makes trading fixed-income more accessible, ultimately improving transparency, efficiency and competition in the marketplace. Changing the way an established industry transacts is no easy feat. There...

MarketAxess's Top Stability & Growth Strengths
Diversified Revenue Streams: Services, post-trade, data, and technology lines showed steady growth with records in 2025 and Q2 2026, and revenue outside U.S. credit plus emerging markets/eurobonds expanded. These trends indicate multiple monetization pillars beyond core U.S. credit.
Strong Market Position & Advantage: Market presence in institutional credit e-trading remains prominent, with leadership in all-to-all and portfolio trading and rising adoption in key workflows. Trading updates cited increased portfolio-trading activity and share alongside broad platform scale.
Innovation-Driven Growth: Newer protocols and tools—such as portfolio trading, block trading, Mid-X, CP+ pricing, and data solutions—are gaining traction and setting record activity levels. Product innovation appears to be a key driver of client adoption across credit workflows.
Perk (formerly TravelPerk) is the intelligent platform for travel and spend management. Built to tackle the time-consuming, manual work that gets in the way of real work, our tools automate everything from travel bookings to expenses, invoice processing, and more. By eliminating this shadow work that wastes hours, erodes morale, and saps innovation, we’re on a mission to power real...

Perk's Top Stability & Growth Strengths
Strong Revenue Growth: Reported metrics show annualized revenue crossing the $300M mark with multi‑year momentum and booking volume at multi‑billion scale. This trajectory signals sustained top‑line expansion through 2025–2026.
Investor Backing & Capital Strength: Fresh equity at a multi‑billion valuation alongside a sizable private credit facility and prior financing provides ample runway for product and market expansion. These transactions are corroborated by independent industry coverage.
Profitability: EBITDA break‑even by the end of 2024 indicates improving unit economics. Subsequent communications highlight margin improvement supported by an AI‑native platform.
Flex, an NYC-headquartered FinTech company, has created a trusted rent payment experience. It’s hard to believe that it’s 2024 and paying rent on time is expensive, inflexible, and difficult; we’re here to change that! We enable our users to pay rent throughout the month on a schedule that better fits their finances and budget, while also helping them build credit....

Flex's Top Stability & Growth Strengths
Strategic Partnerships: Integrations with major property‑tech platforms (e.g., RealPage, Yardi, Entrata, AppFolio) and an Apartment List embed place the product in channels where many U.S. renters already pay or search. Company posts describe sustained rollouts through these partners that support continued user growth.
Market Expansion: New distribution through Apartment List and expanding property‑software integrations indicate wider reach and ongoing expansion in 2026. Company materials cite rising cumulative payment volumes and user counts as these channels come online.
Future-Ready Strategy: The July 24, 2026 application for a Utah industrial bank charter signals intent to reduce funding costs and enable a broader product scope as scale increases. Trade coverage and company materials highlight this as an infrastructure step to support growth.

Karlin Ventures is an early-stage venture capital fund based in Los Angeles. We are value-add partners helping entrepreneurs who take contrarian approaches to create impactful solutions to big, interesting problems. Karlin Ventures is an affiliate of Karlin Asset Management, a private investment firm managing over $1.4 billion of unleveraged equity capital.Our Investment Criteria:Our focus is on education technology, digital media,...

We’re Albert, the simple and reliable way to help you make the right financial decisions. Albert was founded with the goal to democratize financial advice in 2015. With more than 12 million users, our app combines banking, savings, investing, budgeting, and working seamlessly with our team of financial experts – the Geniuses – who provide advice on any financial topic. We...

Albert's Top Stability & Growth Strengths
Product Line Growth: The company offers budgeting, banking via partner banks, savings, investing, identity protection, and short‑term liquidity under its “Genius” assistant. This breadth, comparable to other money super‑apps, indicates expansion beyond its original budgeting/savings focus.
Diversified Revenue Streams: Subscription plans priced at $14.99–$39.99 per month create a different revenue mix than interchange‑heavy neobanks. This model can support higher ARPU if churn and support costs are controlled.
Cost & Operational Efficiency: Leadership shifted from growth‑at‑all‑costs toward efficiency after 2022, pulling back spend and operating with more discipline. This reset suggests tighter cost control during a tougher funding environment.
Provider of a Web-enabled small-ticket lease/loan process for commercial and consumer borrowers on behalf of vendors/manufacturers/distributors that do not have their own in-house finance capabilities

Core Digital Media was founded to empower people to improve their financial lives. Our websites QuickenLoans.com and LowerMyBills.com provide consumers valuable information and company connections as you navigate life's biggest financial decisions.

Core Digital Media's Top Stability & Growth Strengths
Strong Revenue Growth: Parent segment trend shows a sharp jump in 2025 within Rocket’s “All Other” segment that includes CDM, suggesting rising throughput for the unit. Rocket’s broader revenue rebound in 2024–2025 supports higher budgets and volumes flowing through CDM’s marketing engine.
Strong Market Position & Advantage: Filings describe CDM as a key engine for digital lead generation (e.g., LowerMyBills) supplying millions of leads, underscoring its strategic importance inside Rocket. This embedded role positions CDM to benefit when the parent’s topline and market share improve.
Strategic Partnerships: CDM operates as an integrated subsidiary within Rocket Companies alongside brands in the “All Other” segment. This alignment provides captive demand and cross‑brand synergies that can enhance conversion and resilience.



